 Subscribe
Australia’s rate rises hit harder as mortgage debt climbs

- The cash rate is now at its highest level since 2011, as the RBA continues to battle stubborn inflation.
- Australians are carrying much larger mortgages than they were 15 years ago, making households more sensitive to every rate increase.
- A further 25-basis-point hike would add about $125 a month to repayments on a $750,000 mortgage, if passed on in full.
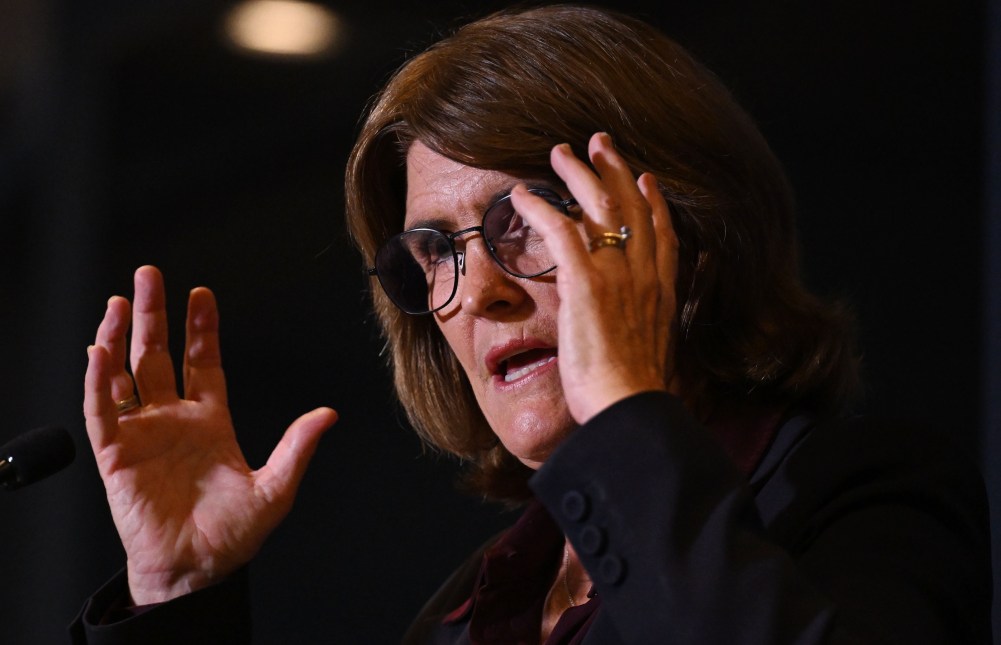
Last week, the Reserve Bank delivered one of its most significant rate moves in years, pushing borrowing costs to their highest level since 2011 and ending a pause in place since May.
The RBA board voted unanimously at its September meeting to lift the cash rate, its primary tool for combatting inflation, by 25 basis points to 4.60 per cent. It was the fourth increase this year, taking total rate rises in 2026 to a full percentage point.
While the central bank may not be finished, it is caught between a rock and a hard place. The central bank must raise interest rates to fight stubborn inflation, but higher borrowing costs risk pushing a slowing domestic economy towards a recession.
For those with a variable-rate mortgage, the impact is near-immediate, as repayments are directed more towards interest than principal. That’s tough for borrowers who could face another round of higher repayments in November, according to market estimates.
Though the cash rate is back at levels last seen in 2011, the burden on borrowers is much heavier today. The average new owner-occupier mortgage has roughly doubled since then, from about $363,000 to more than $730,000, while wages have risen far more slowly. That means each rate rise now lands on a much larger debt pile.
Announcing its September 29 rate rise, the RBA board said it will “continue to do what it considers necessary” to bring inflation back to its target band of 2 to 3 per cent.
A day later, the Australian Bureau of Statistics reported that annual headline inflation, a broad measure of price rises across the economy, rose to 4 per cent in August, up from 3.5 per cent in July.
Rock and a hard place
The RBA has repeatedly warned that strong public spending can add to demand in the economy, potentially making inflation harder to bring down. The government, however, argues that much of its spending is necessary and that a broader mix of domestic and global pressures is driving inflation.
Those pressures include the Middle East conflict that global markets must contend with, which continues to restrict global oil supply chains with no clear end in sight.
In a statement last week, RBA Governor Michele Bullock said the conflict had “broadened,” and global energy prices are now much “higher than had been assumed” in the bank’s previous forecast.
Higher energy and fuel costs, housing pressures, supply-chain disruptions, rising labour costs and more expensive imports are all adding to cost-of-living pressures for ordinary Australians.
Domestic pressures are also keeping inflation elevated, including housing shortages, rising rents, weak productivity and an economy where labour and business capacity remain stretched.
That is why the RBA is still focused on underlying inflation. Trimmed mean inflation, which strips out the largest price rises and falls to give a clearer picture of underlying price pressures, was 3.6 per cent in August, above the RBA’s 2 per cent to 3 per cent target range.
The pain falls most heavily on borrowers. About 35 per cent of Australian households have a mortgage, according to the Australian Institute of Health and Welfare, and those with variable-rate loans pay more when official rates rise.
For someone with a $750,000 mortgage over 30 years, another 25-basis-point increase would add roughly $125 a month, or about $1,500 a year, to repayments if passed on in full.
Higher rates also make it more expensive for businesses to borrow, which can slow investment and hiring.
Governments can ease pressure on the economy through other means, including lower spending or tax changes, but the cash rate remains the RBA’s quickest and bluntest tool.
For mortgage holders, that means the fight against inflation is still being fought through higher repayments, and there may be more pain to come.
Topics: Debt, Interest Rates, Mortgage